Home Blog

From a Sewing Machine to Top Nigerian Children’s Clothing Brand: The Story of Ruff ’n’ Tumble

0

In 1996, Adenike Ogunlesi was looking for good-quality pyjamas for her three young children. The options available in Nigeria did not meet what she wanted in terms of quality, durability and style, so she decided to make them herself.

The first set was made from cotton, with colourful fabric, lace and a Peter Pan collar. Her sister-in-law liked what she saw and ordered seven pairs. Soon, Ogunlesi began wondering whether other parents might also be willing to buy them.

She started selling the clothes from the boot of her car after dropping her children at school. She also took them to church bazaars and school markets, gradually expanding beyond pyjamas into trousers, shorts, shirts and skirts.

“I took all my kids’ clothes apart to see how they were made, developed patterns out of some of them, and just started making trousers, shorts, shirts and skirts, and all kinds of things,” Ogunlesi recalled.

One market changed the way she viewed the opportunity.

Ogunlesi had taken about ₦120,000 worth of clothes to a market and sold almost all of them. The sales made her realise that the demand could extend beyond the people who already knew her.

“I just closed my eyes to everything else and thought: ‘Okay, what exactly is going on here? There must be other people with this need,’” she said.

She began looking more closely at the children’s clothing market. At the time, she found that the available options were limited, with little variety in colours and designs. She wrote down what she believed competitors were doing well and where she thought they were falling short.

“At the time, I didn’t realise that what I was doing was market research,” she later explained to Harvard Business School. She visited places where children’s clothing was sold, looked at the products, compared prices and considered what she could do differently.

One of the gaps she noticed was the way children’s outfits were being sold. Many came as three-piece sets, leaving parents with little flexibility to combine different pieces.

Ogunlesi decided that customers should be able to buy individual pieces and create their own combinations.

“So I thought if all they want is a shirt, they should buy the shirt and be able to mix it with the shorts or trousers of their choice – just to be free to create a style for their kids, the way they would like their kids to be dressed,” she said.

That approach became part of what differentiated the brand.

From the boot of a car to a store

As demand grew, Ogunlesi moved beyond selling from her car. She hired tailors and began producing clothes for a supermarket, where she was given a section to display the products.

The experience did not meet her expectations.

She noticed that customers tried on the clothes and left them on the floor, leaving the area untidy. For Ogunlesi, it showed that building a good product also meant paying attention to how customers experienced the brand.

In 1998, she opened her first Ruff ’n’ Tumble store in Lagos, using her personal savings and money borrowed from her older brother.

The store soon gave her another indication of the demand for the brand. During Christmas, a long queue formed outside the shop. She rented the space next door and expanded the store.

From there, Ruff ’n’ Tumble continued to develop its operations and reach more customers. The company introduced computerisation and an enterprise resource planning system, began keeping customer information and followed up with customers after their purchases, including those who had not returned to the stores.

The business expanded from Lagos to Abuja, Port Harcourt, Ibadan and Kano. By 2015, Ruff ’n’ Tumble had become a recognised children’s clothing brand in Nigeria and employed more than 200 people.

Building clothes that last

For Ogunlesi, durability became an important part of the brand’s identity.

She wanted children to be able to wear the clothes repeatedly and pass them down to younger siblings.

“As a mother, durability is key. I didn’t want clothes that after two or three washes are finished,” she said.

That focus on quality has remained part of how she describes Ruff ’n’ Tumble. In later interviews, she has spoken about the importance of researching global trends while paying attention to local tastes and culture. The company also distinguishes between its customer, usually the parent buying the clothes, and its consumer, the child wearing them.

The company has since expanded beyond retail. Through Gatimo Apparel, Ogunlesi has developed garment manufacturing capacity, while the Betti-Okuboyejo Foundation provides garment-making and entrepreneurship training for young people.

For a business that began with children’s pyjamas, the progression has been substantial. Yet Ogunlesi’s story is also a record of how a business can evolve by paying attention to its customers, studying its market and continually improving its standards.

Her own path into entrepreneurship was also shaped by a willingness to make a difficult decision. She was originally expected to become a lawyer but left law school after two weeks because she knew it was not the path she wanted. Entrepreneurship, she later said, gave her the “freedom to create your own universe” and “the power of choices.”

That willingness to move forward has also shaped how she thinks about mistakes. “Don’t stay in that place, just move on,” she said when discussing setbacks. For her, the important thing is to acknowledge what went wrong, learn from it and keep sight of what she wants to create.

That philosophy can be traced through Ruff ’n’ Tumble’s history. A need for better pyjamas led to a few pairs of children’s clothes. Selling from the boot of a car led to studying the market. Studying the market led to a clearer understanding of what parents wanted. As the company grew, the same attention to quality, customer experience and adaptation continued to shape what came next.

That may be the most useful part of Adenike Ogunlesi’s story for anyone building a business today: the idea may start small, but the standard you set for it does not have to be.

Keep defining, redefining, refining and evolving.

The Brief Network: Inspiring Stories and Empowering Lessons.
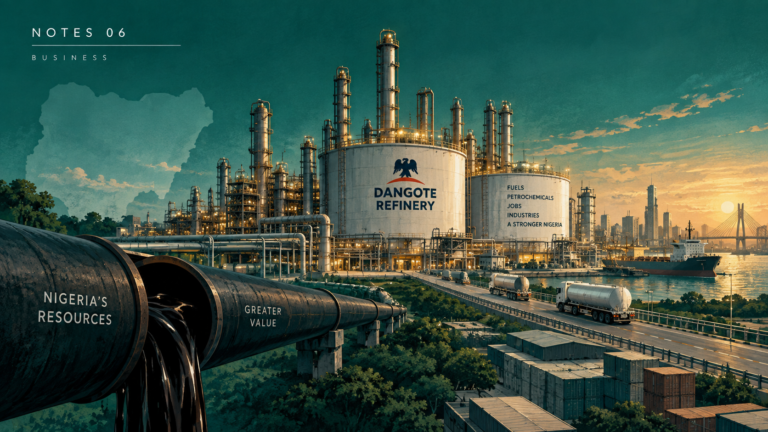
Nigeria has had Oil for 70 Years. The Dangote Refinery IPO Shows us where the Real Value is.

Dangote Refinery is about to go public in what is expected to be Africa’s largest IPO.

About 4.1 billion shares are being offered at ₦525 each, potentially raising approximately ₦2.15 trillion. The money will help fund the refinery’s next stage of expansion, with plans to increase capacity from 700,000 barrels per day to 1.4 million by 2029.

Those are big numbers. But something else interests me about this IPO – what sits underneath the numbers.

Nigeria discovered commercial quantities of oil in 1956, and by the 1970s, the oil boom had transformed the country’s finances. What that moment could have meant for Nigeria’s industrialisation is a conversation for another day.

For decades, we produced crude oil, exported it, and imported significant quantities of the products made from it. We had something enormously valuable. But having something valuable and creating value from it are two very different things.

When oil changed everything

Growing up in Nigeria, I remember my mother repeating something General Yakubu Gowon was said to have declared during the oil boom years:

Money is not our problem, but how to spend it.

I did not fully understand what that meant then. Nigeria had oil, and at one point, so much oil revenue that the problem was reportedly how to spend the money.

Decades later, perhaps the more important question is the one we should have been asking all along:

What are we going to build with it?

Because for all the crude Nigeria produced, we eventually found ourselves in an extraordinary position. We exported the raw material and imported much of what it became. This is where the Dangote Refinery story becomes more interesting than one company or one billionaire.

Nigeria is exporting more of what it once imported. The numbers show a major shift in petroleum-product trade.

In 2023, Nigeria exported an average of about 46,000 barrels of petroleum products per day by sea. By the second quarter of 2026, that had risen to approximately 350,000 barrels per day. At the same time, seaborne petroleum-product imports fell from nearly 400,000 barrels per day in 2023 to below 130,000 barrels per day in the second quarter of 2026.

The U.S. Energy Information Administration says production from Dangote Refinery has driven much of that change. Think about what happened here.

Nigeria did not discover oil in 2023. It increased its capacity to do something with the oil it already had.

That distinction is at the heart of industrialization.

The economic value of a resource is not determined only by how much of it you have. It is also determined by what you are capable of doing with it.

The further you move up the value chain, the more value you create. Extract crude and there is value. Refine it and there is more. Build industries around its derivatives and the value chain extends further, creating opportunities for businesses, skills, jobs, exports and products that serve the domestic economy.

The same principle applies far beyond oil.

A country can grow cocoa and export the beans, or develop industries that turn cocoa into higher-value products. It can produce cotton and build textile industries around it. It can possess minerals and develop the expertise and infrastructure required to process them.

The question is:

Where do we stop in the value chain, and what would it take to move one step further?

Now the refinery itself is entering another value chain

This is why the IPO matters.

Dangote Refinery began as a privately financed industrial project. It became a productive asset, supplying the Nigerian market and exporting refined products. Now part of that asset is being opened to public investors while the company raises capital for further expansion.

That is another important part of the industrialization story because industrialization needs capital. Capital markets can move savings into productive enterprise. Businesses gain money to invest and expand, while investors get the opportunity to own part of the value those businesses create.

That does not mean every IPO is a good investment. The larger point is that a productive Nigerian asset is now seeking trillions of naira from the capital market to help finance its next stage of growth.

Saudi Arabia offers an interesting historical comparison.

The Saudi government completed its acquisition of Aramco in 1980. In the decades that followed, Aramco expanded beyond producing and exporting crude into refining, petrochemicals and other downstream activities.

Aramco itself describes this evolution as becoming an integrated petroleum enterprise, with downstream investments designed to capture more value across the hydrocarbon chain. In 2019, Saudi Aramco went public, allowing outside investors to own part of the company.

The lesson worth paying attention to is:

Having the resource was never the end of the story. What matters is the productive capacity built around it.

One refinery can have an impact far beyond refining

One refinery does not make an industrial economy. But an industrial project of this scale can move an economy further in that direction. Its value is not limited to the petroleum products coming out of the refinery.

A project of this size creates demand around it. It needs engineers, technicians, transporters and suppliers. It creates opportunities for logistics, storage, maintenance and other supporting services. And when locally refined petroleum products become more available, the effects can travel further into an economy.

Transportation costs affect the price of moving goods. Energy costs affect businesses. Petrochemical inputs feed other industries. Increased exports can bring in foreign exchange, while replacing some imports can reduce the amount leaving the country to buy products it could produce itself.

These are called spillover effects in economics. They are part of what makes industrial investment important.

The real opportunity, then, is not simply to build another refinery. It is to create more productive assets around the things Nigeria already has, while developing the infrastructure, skills, capital and supporting businesses that allow their value to spread through the economy.

Some will be enormous industrial projects. Others will emerge because those projects exist in the first place. That is how one investment can begin to create value far beyond itself.


More than fifty years ago, Nigeria reportedly had so much oil revenue that the problem was how to spend it. Perhaps the more consequential question was always:

What can we build with it?

That is why the Dangote Refinery IPO interests me beyond the ₦2.15 trillion offer.

Nigeria did not suddenly acquire a new natural resource. What changed was our capacity to transform one we have had for decades. That capacity is serving more of our needs at home, selling more products abroad, and now seeking public capital to expand further.

And the lesson extends far beyond oil.

What a country learns to do with what it has matters more than what it has. Because until you can create value from what you have, having it is not enough

Notes with STB | A content series exploring mindset, money and business.


The Brief Network: Inspiring Stories and Empowering Lessons.

LEGO Nearly Went Bankrupt. Here’s What Its Turnaround Can Teach Business Owners

0

LEGO is one of the most recognisable toy brands in the world today. Its colourful bricks are found in homes, schools and playrooms across the globe.

But in the early 2000s, the company was struggling to survive.

LEGO had expanded aggressively into new products, markets and businesses. It had moved beyond its traditional building bricks into video games, clothing, watches, theme parks and other ventures. The expansion made the company bigger, but it also made the business more complicated and expensive to operate.

By 2003, LEGO’s sales had fallen by 26 percent, from DKK 11.4 billion to DKK 8.4 billion. The company recorded a pre-tax loss of DKK 1.4 billion. Its financial position had become so serious that the company was facing a debt burden of roughly $800 million.

LEGO had spent years trying to become more than a toy company. In the process, it had started losing control of the business it already had.

When Growth Became the Problem

LEGO’s expansion was not necessarily a bad idea.

The company had a powerful brand, a loyal customer base and a product that had been successful for decades. Extending that brand into new areas seemed like a reasonable way to create more revenue.

But by the early 2000s, LEGO had moved far beyond its core business. It was operating LEGOLAND theme parks in several countries, producing branded clothing and accessories, developing video games and creating television and film content. It had also expanded into company-owned retail stores, books and magazines.

LEGO was no longer simply selling building bricks. It was trying to build an entire entertainment ecosystem around the brand.

The problem was that expansion brought complexity with it. Every new business required money, people, management and attention. Some of these ventures were not generating enough returns to justify what they consumed. At the same time, LEGO’s core toy business was struggling with changing consumer habits, stronger competition and pressure from retailers.

The company had more products and more activities, but it was becoming harder to manage the business profitably.

LEGO had created more ways to make money, but it had also created more ways to lose it.

The company had too many products, too many variations and too much inventory. Its manufacturing system had become increasingly complicated, while some of its new ventures were performing poorly.

LEGO’s own 2003 annual report acknowledged that its growth strategy had contributed to the loss of market share.

The issue was no longer simply how to grow. It was how to regain control of a business that had become too complicated.

The Decision to Change Direction

In 2004, LEGO began a major turnaround.

Jørgen Vig Knudstorp became CEO and helped lead the company towards a simpler and more disciplined business model. Instead of continuing to expand in every possible direction, LEGO began returning its attention to its core business.

The company cut costs, reduced its workforce, sold assets and simplified its product portfolio. It also became more deliberate about what it produced and how it produced it.

LEGO sold LEGOLAND Parks to improve its financial position. It reduced its production and operating costs substantially and began eliminating products that were not contributing enough to the business.

The company wasn’t abandoning innovation. It was becoming more selective about where innovation happened.

The question changed from “What else can LEGO do?” to “What does LEGO do best, and how can we do that better?”

LEGO’s turnaround was not achieved by abandoning creativity. It was achieved by bringing discipline back into the creativity.

The company continued developing new products and experiences, but increasingly built them around the strength of its core building system.

And the results followed. By 2010, LEGO had eliminated its debt. By 2015, it had become the world’s most valuable toy company, surpassing Mattel in brand value.

The company that had once been struggling to survive had become one of the strongest brands in the global toy industry.

What This Means for Your Brand

LEGO’s story is useful for any founder or business owner whose company is growing, expanding or trying to recover from a difficult period.

1. Don’t confuse expansion with progress

Adding a new product, entering another market or starting another business can make a company look bigger.

But bigger does not automatically mean healthier.

Every new product requires money, people, attention, marketing and management. If the returns do not justify those resources, expansion can weaken the business instead of strengthening it.

Before adding another thing, ask whether the things you already have are performing as well as they should.

2. Your core business deserves attention

When a business starts growing, there is often pressure to chase the next opportunity.

LEGO’s experience shows why founders should be careful about that instinct.

The core product is usually where a company has its strongest knowledge, customer relationships and competitive advantage. Moving away from it too quickly can mean abandoning the very thing that made the business valuable.

Expansion should strengthen the foundation, not distract you from it.

3. Not every product deserves to survive

Businesses can become emotionally attached to their own ideas.

A product may have taken months to develop. A new service may have required a significant investment. A particular project may have been the founder’s favourite idea.

None of that guarantees that customers want it.

LEGO’s turnaround required difficult decisions about products and activities that were adding complexity without enough return.

For a brand, knowing what to stop can be just as important as knowing what to start.

4. More choice can create more problems

A larger product catalogue can appear attractive because it gives customers more options.

But every additional variation creates operational demands.

More inventory has to be managed. More products have to be marketed. More decisions have to be made. More resources become scattered across different priorities.

A business does not become excellent simply because it offers more. At times, reducing complexity gives a company the room to improve what matters most.

5. Innovation works better when it has a foundation

LEGO did not solve its problems by becoming less creative. It became more disciplined about where its creativity was applied.

That is an important distinction for brands.

Innovation does not always mean abandoning the old model for something completely new. It can mean finding new ways to make an existing strength more valuable.

For LEGO, the brick remained at the centre. New ideas could then build around it.

The strongest extensions of a brand should make the core business stronger, not make customers forget what the brand stands for.

6. Know when to simplify

There is a point in the life of many businesses where complexity starts to look like success.

The company has more employees, more products, more departments, more partnerships and more markets.

But underneath all of that, the business may be becoming harder to manage.

LEGO’s turnaround shows that simplification is not necessarily a retreat.

Sometimes it is a way of getting back in control.

The Bigger Picture

LEGO’s near-collapse was not caused by a lack of ideas.

It had plenty of ideas.

Its problem was knowing which ideas deserved the company’s money, attention and energy.

The turnaround came when LEGO became more disciplined about growth, returned its focus to its core strengths and made difficult decisions about what needed to go.

That is perhaps the most useful lesson for a growing brand.

You don’t have to pursue every opportunity. You have to recognise the opportunities that make your business stronger.

LEGO nearly lost everything by trying to become too many things at once.

Its recovery began when it remembered what it was best at.

The Brief Network: Inspiring Stories and Empowering Lessons.
A janitor quietly built an $8 million fortune. Here’s what his story teaches us about building wealth.

Ronald Read drove a second-hand Toyota Yaris, dressed in worn flannel shirts, and was known to hold his coat together with safety pins. He spent decades working at a gas station and later worked for seventeen years as a part-time janitor at a J.C. Penney in Brattleboro, Vermont.

He read the Wall Street Journal every day and was a regular at his local library. He did not have a financial advisor, a college degree, or a Wall Street connection.

When he died in June 2014 at the age of 92, his estate was worth nearly $8 million. He left $4.8 million to Brattleboro Memorial Hospital and $1.2 million to the town’s Brooks Memorial Library, the largest bequests either institution had ever received at the time. (NBC News, 2014; TODAY, 2015)

His own family was, in the words of his stepson Phillip Brown, tremendously surprised.

Read quietly bought stocks for decades, building a remarkably diversified portfolio over time. He eventually owned at least 95 stocks, including Procter & Gamble, Johnson & Johnson, J.M. Smucker, JPMorgan Chase, General Electric, Dow Chemical and CVS Health.

He favored companies and businesses he understood. He reinvested his dividends. And he held many of his investments for years, even decades, through multiple market cycles. (CNBC, 2016; The Big Picture, 2015)

There was no strategy meeting, no pivot, no dramatic moment of insight. There was a man in a flannel shirt, reading the Wall Street Journal, making patient decisions that no one around him could see adding up to anything.

Wealth built slowly produces very little worth showing while it is being built. There is no dramatic before and after. No funding round. No exit. No single milestone that looks particularly significant from the outside.

There is only the long, quiet accumulation of good decisions made consistently across a timeline that many people are not willing or patient enough to hold.

And perhaps that is one reason stories like Ronald Read’s matter.

We are surrounded by the visible moments of wealth: the company sale, the investment that exploded, the property portfolio, the person who seemingly became successful overnight.

We see the outcome because outcomes make a scene. What we don’t see are the years of small, ordinary decisions quietly compounding into something significant

Getting rich slowly is one of the most established paths to building wealth, and one of the least glamorous.

No one is going to congratulate you every month for buying another investment, reinvesting another dividend, leaving the money alone and doing it again. The account does not care whether anyone is watching and that may be the bigger lesson in Ronald Read’s story.

Wealth does not need to look impressive while it is being built.

Sometimes it looks like the same ordinary decision, made over and over again, for an extraordinarily long time.

Start somewhere, regardless. Stay with it long enough to see what it becomes.

Until the next note,

– STB

References:

  • NBC News (2014), Vermont ex-janitor bequeaths secret millions to library and hospita
  • TODAY (2015), Secret millionaire: Vermont janitor bequeaths fortune to hospital, library
  • CNBC (2016), A janitor secretly amassed an $8 million fortune and left most of it to his library and hospita
  • The Big Picture / Ritholtz (2015), The Remarkable Life and Investing Lessons of Ronald Read

The Brief Network: Inspiring Stories and Empowering Lessons.
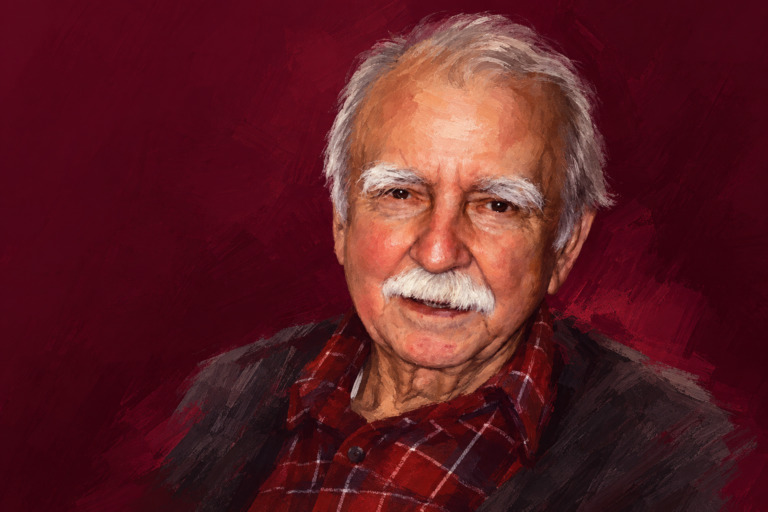
American Shoe Stores Rejected Birkenstock. Margot Fraser Found Another Way In

In 1966, Margot Fraser was not looking for a business opportunity.

She was looking for relief.

The German-born designer was visiting her home country from California when she stopped at a health spa in Bavaria. She had been dealing with chronic foot pain, the kind that came from years of wearing constrictive shoes while working as a dress designer. Someone at the spa recommended a strange-looking pair of German sandals called Birkenstocks.

They were not fashionable. They were not elegant. They certainly did not look like the kind of footwear that would one day become a global fashion icon.

But when Fraser put them on, something changed. The sandals relieved the pain in her feet, and she immediately understood that there was something different about them.

What happened next would take far more than simply liking a product.

Fraser took the sandals back to California, and she decided to sell them.

At the time, Birkenstock was already an established German footwear name, but it had little presence in America. Fraser saw a possibility that most people around her did not see. If these strange-looking sandals could make her feet feel this much better, perhaps other people were looking for the same thing.

She later admitted that she did not know exactly what she was getting herself into.

“I didn’t realize what it would take or how I would do it,” she said in a 1998 interview, “but I thought that this had great potential right from the beginning.”

That sentence captures much of what made Fraser’s story remarkable.

She did not have a detailed blueprint for building a footwear empire. She had no established American distribution network waiting for her. She simply had a product she believed in and the conviction that other people might need it too.

The obvious problem was that the people she needed to convince did not see what she saw.

When Fraser approached mainstream shoe retailers, many were skeptical. The sandals looked too strange, too clunky and too unfashionable. In an industry where appearance mattered enormously, Birkenstocks seemed to be selling the opposite idea.

Why would anyone choose an awkward-looking sandal when there were prettier shoes available?

So Fraser changed the question.

Instead of spending all her energy trying to convince traditional shoe stores that Birkenstocks were fashionable, she looked for people who would care about what the sandals actually offered.

She found them in health-food stores, health fairs and among consumers interested in fitness, natural living and comfort. She began selling the sandals through these alternative channels and at weekly markets.

It was not the glamorous beginning people might imagine when they think about a global footwear brand.

Fraser started from home in Santa Cruz. Her garage became a warehouse. She and her husband had to move their cars out to make room for boxes of sandals. She sold the product through word of mouth and small-scale events, gradually introducing more Americans to something they had never considered wearing before.

The early business was remarkably small.

In 1972, Fraser founded BIRKENSTOCK Footprint Sandals Inc., which became the foundation of what is now Birkenstock USA. At one point, she operated from a small office above a health-food store in San Rafael, paying just $25 a month in rent and working with one part-time employee.

But something was beginning to happen.

The people who tried the sandals kept talking about them.

Customers who cared less about whether their shoes looked conventional and more about whether they felt good began embracing them. The sandals found a natural audience among the counterculture of the late 1960s and 1970s, eventually becoming associated with the broader back-to-nature movement. What mainstream retailers initially dismissed as unattractive footwear was finding its own community.

Fraser had not changed the sandals.

She had changed where she was looking for people who would understand them.

That distinction matters.

The truth is that the first rejection of an idea is not proof that the idea is bad. At times it simply means you are presenting it to the wrong audience.

Fraser could have interpreted the rejection from traditional shoe retailers as a sign that Birkenstock would never work in America. Instead, she found another route into the market. She paid attention to the people who were already responding to the product and built from there.

Her growing sales eventually caught the attention of Karl Birkenstock. In 1974, he signed an import agreement making Fraser the sole US importer of the sandals.

The woman who had started by bringing a few pairs home from Germany was now building the American business of a brand that had once looked completely out of place in the American footwear market.

And she was only getting started.

Over the following decades, Birkenstock moved far beyond its early association with health-food stores and hippie culture. Fraser helped build a professional distribution and sales operation, while the sandals gradually reached customers who had once dismissed them. By 1990, her company was importing hundreds of thousands of pairs annually and distributing them to more than 1,000 retailers across the United States.

The irony is difficult to miss.

The same footwear that had once been criticised for being ugly eventually became recognisable almost everywhere.

But perhaps the most interesting part of Margot Fraser’s story is not that Birkenstock eventually became popular.

It is that she believed in its value before popularity arrived.

She had experienced the product herself. She understood the problem it solved. And rather than waiting for everyone else to agree with her, she started looking for the people who needed what she had discovered.

That is a very different way of seeing opportunity.

What Margot Fraser’s story teaches us

We often imagine opportunity arriving looking like opportunity. It does not always. It can look strange, unimpressive or even unattractive, especially when others do not yet see its value.

Margot Fraser did not invent Birkenstock. She discovered it, experienced its value and believed others would too. When mainstream retailers dismissed the sandals, she found people who understood what she saw and built from there.

Her advantage was not knowing exactly what the future would look like. It was acting on what she could already see.

Fraser’s story reminds us that we do not always need to create something new to create something meaningful. At times, the opportunity is recognising value before others do, believing in it enough to pursue it, and finding the people who will understand it.

You do not need everyone to believe in what you are building at the beginning. You need enough conviction to keep moving while you find the people who do.

The Brief Network: Inspiring Stories and Empowering Lessons.
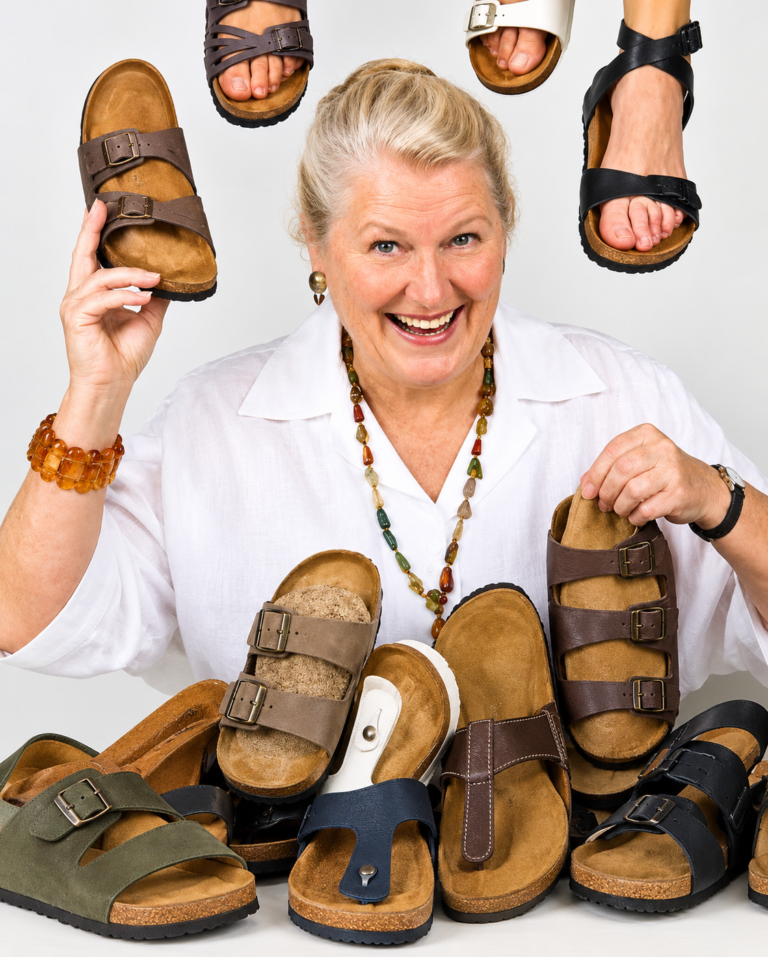
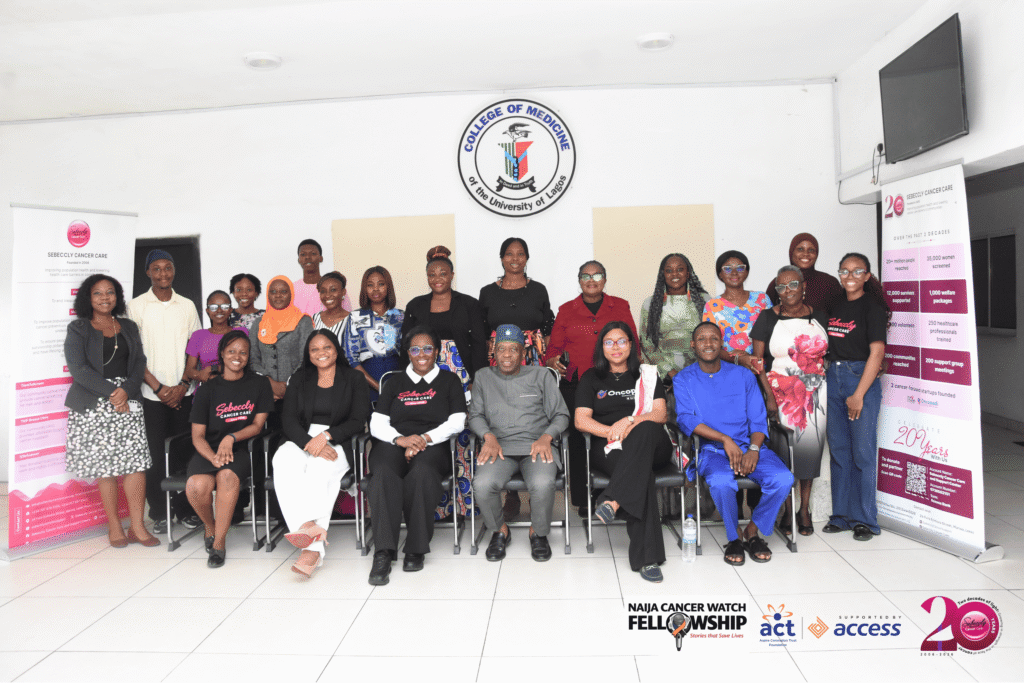
From One Cancer-Care Mission to an Ecosystem: The Dr. Omolola Salako Story

When Dr. Omolola Salako started Sebeccly Cancer Care in 2006, she wasn’t executing a carefully mapped-out plan to build an ecosystem of cancer-care organisations. She was responding to something deeply personal.

Three years earlier, she had cared for her younger sister during her battle with kidney cancer. The experience was painful enough that she wasn’t initially certain she wanted to dedicate her career to oncology.

But something began to change as she volunteered in cancer-care institutions and NGOs. At the time, she says, Nigeria had fewer than 30 oncologists. She felt a nudge to become one of them.

In 2006, she established Sebeccly Cancer Care to provide supportive care to cancer patients and their family caregivers.

Twenty years later, that first step has grown into something much bigger. But according to Dr. Salako, there was never a complete roadmap.

“Looking back, I didn’t have a clear roadmap, but I always followed my heart.”

What she did have was an approach to problems.

“I believe in creating practical solutions and generating knowledge to solve problems.”

And so she learned to identify particular problems, analyse them and experiment with practical ways of solving them. Not every problem could be tackled. But when a problem was particularly disturbing and a practical solution appeared possible, she and her team went to work.

One problem at a time

One of those problems was access to breast and cervical cancer screening.

The response became Time-to-Screen, Sebeccly’s flagship women’s cancer screening programme. Through a partnership with ACT Foundation, Salako says the programme has provided free screening and treatment to more than 35,000 women across 100 communities.

Another challenge was the myths and misconceptions surrounding cancer prevention.

That led to initiatives including the 12K LLP Guinness World Record attempt, the Cancer on the Street podcast and community cancer outreaches.

More recently, the organisation identified another problem: cancer patients needing financial assistance and the challenge of ensuring that public generosity reaches people with genuine medical needs. The response is Kind Gifts, a medical crowdfunding platform being developed to verify funds received before disbursing them to patients requiring financial assistance.

Different problems. Different solutions. But the same underlying approach.

“Today, the problems we are solving are centered around people’s needs and what the community needs.”

The ecosystem wasn’t the original plan

When asked whether she always envisioned building these different organisations – Sebeccly Cancer Care, Oncopadi and Pearl Oncology Specialist Hospital, her answer is straightforward:

“The simple answer is no.”

There were, however, clues. She remembers being entrepreneurial from childhood, selling sweets and clothes and later launching a profitable business centre while at university.

Then came September 6, 2006. On her way out of Akwa Ibom, Salako says she had a divine vision of creating a place where cancer patients would be cared for. Initially, she understood that vision to mean an NGO. Over time, her understanding expanded.

She began to see what she describes as a sanctuary integrating different dimensions of a patient’s life – from spiritual care and relationships to financial and emotional support, recovery and rehabilitation – within comprehensive cancer treatment.

The next pieces would reveal themselves gradually. While practising as an oncologist, she noticed something during one particular clinic day. Many of her patients walked into the clinic holding their phones. It triggered what she describes as a eureka moment.

What if cancer patients could use technology to improve their outcomes?

That question led to the birth of Oncopadi in 2017. Fourteen years after the vision she had in 2006, she says the time finally felt right to launch Pearl Oncology Specialist Hospital.

Along the way, her work with patients continued to generate other ideas.

The GIFTS framework, which she began using to counsel patients at Sebeccly in 2012, eventually became the book GIFTS of Survivorship: You Are Bigger Than Cancer.

Then, in 2026, the Oncopreneurs Multi-Cooperative Society was formed with the goal of creating wealth among its members, including through investment in cancer care, cancer specialists and new cancer ventures.

What now looks like an ecosystem emerged one solution at a time.

“I didn’t set out in the beginning to develop an ecosystem.”

Instead, she says she remained focused on strengthening cancer care through innovation, partnerships and, perhaps most importantly, consistency.

Her description of entrepreneurship is particularly revealing:

“For many entrepreneurs like myself, it’s never clear in the beginning.”

But she adds:

“When you honor the assignment of today, even though it gets tougher, it also gets easier. And you reap the fruits of your labour.”

Sometimes you have to step outside the system to improve it

Dr Salako has worked across public and private healthcare, research and biotech companies, and the social sector. She has experienced the system as a clinician, researcher, advocate and entrepreneur. Being inside clinical care showed her the everyday challenges faced by cancer patients, and the sacrifices demanded of the specialists caring for them. It also taught her the importance of institutions, standards, regulation, research, professional networks and the decades of knowledge embedded within established systems. But being inside a system can also expose its limitations.

“Innovation is always ahead of tradition.”

For Salako, that creates a tension innovators must learn to navigate. You need the system. You need its knowledge. You need collaboration with clinicians, researchers, policymakers, advocates and other stakeholders. But there may also come a point when solving a problem requires building differently.

“Every innovator has to decide at what point they want to build differently and step away from the system.”

The answer, she argues, is not in abandoning the system entirely but in knowing when to remain grounded within it and when to step outside it long enough to create something that can ultimately benefit it.

Twenty years of not giving up

On September 6, 2026, Sebeccly Cancer Care turns 20. On this she says:

“I’m most proud that I never looked back and I never abandoned Sebeccly, even though there were moments when it was tempting to do so.”

The early years weren’t easy. There were periods when donations and runway disappeared. She was encouraged to shut Sebeccly down and concentrate on becoming a cancer specialist. She refused.

“No pressure could stop me from believing in Sebeccly.”

The experience became an education in entrepreneurship. Sebeccly taught her, she says, about starting with nothing, believing in an idea, managing limited resources, attracting more resources and transforming passion into processes. It also taught her that impact without sustainability can eventually undermine the very people you’re trying to help.

She learned that lesson through a patient-access programme offering a particular cancer drug at a discounted rate. As patients appealed for more assistance, she and her team began providing the drug free to those who couldn’t afford it. Eventually, they had donated about 60% of the drugs. It felt like impact. But there was a problem.

The programme wasn’t generating enough money to purchase the next order.

Eventually, it ended. And when patients subsequently needed the drug at a discounted rate, the programme could no longer help them either. The experience changed the way she thought about doing good.

“Whilst it’s important to provide the solution, it’s equally important to sustain it.”

That lesson would influence what came next. Rather than thinking about Sebeccly only as an NGO dependent on donations, the organisation began serving as a launchpad for other ventures.

  • Oncopadi Technologies followed in 2017.
  • Pearl Oncology Specialist Hospital followed in 2021.

Other initiatives followed.

And today, Sebeccly is working towards establishing its permanent site. Twenty years after starting, Salako says:

“We are stronger as a foundation. We have more assets, and whenever I step down from Sebeccly’s management, which is very soon, Sebeccly will outlive me abundantly.”

20 years and the next 1,000

Sebeccly is marking its 20th anniversary – 20 in 26 – as a launchpad for what comes next.

The initiatives include the Naija Cancer Watch Fellowship (NCWF), a three-month programme designed to improve evidence-based cancer reporting and public-health storytelling; KindGifts, the medical crowdfunding platform; and the P.O.W.E.R Conference, focused on prevention, oncopreneurship, women’s health, emerging technologies and research.

There is also the Oncopreneurs Collective: Its ambition is significant: identify and mentor the next 1,000 oncopreneurs and cancer specialists who can build the systems and institutions required for sustainable healthcare delivery.

After 20 years of building, perhaps this is the natural next chapter.

The woman who began by trying to solve problems herself is now thinking about the people who will solve the problems after her. And perhaps that is one of the most interesting things about her journey.

She began with an assignment she believed mattered. Then she kept showing up. One problem revealed another. One solution created the foundation for another. Experience sharpened the vision. And what once looked like separate projects gradually began to reveal a much bigger picture. As she puts it:

“Ultimately, the blueprint is divinely inspired; my real job is to execute it with faith.”

Twenty years later, she is still executing. But increasingly, she is also building the people, ventures and institutions that can continue long after she steps away.


The Brief Network: Inspiring Stories and Empowering Lessons.
You’re probably wasting your best hours and working longer may not be the answer.

Almost 20 years ago, I stumbled across a Harvard Business Review article that completely flipped how I view productivity. It was Tony Schwartz and Catherine McCarthy’s 2007 piece, Manage Your Energy, Not Your Time.

Their core argument was simple but practical: Time is completely finite. You get 24 hours, and that’s it. Energy, however, is a renewable resource. I realized then that when you deliberately manage your focus and stamina, those same 24 hours yield entirely different results.

That single insight changed everything for me.

Here is how I applied the research.

First, I figured out my peak hours, that specific window of the day when my thinking is sharpest and my decisions are clearest. Second, I started protecting that window fiercely. I dedicated it solely to the work that matters most.

Running multiple businesses while being a mom among other things, means the demands on my time are constant, loud, and competing. The only way to stay ahead is to be ruthless. By giving my prime hours to high-level tasks, I can spend far less time executing them inside my peak window than if I tried forcing them at other times of the day.

I didn’t necessarily work less overall. Instead, I aligned my focus with my stamina.

Research completely backs this up. In 2014, Stanford economics professor John Pencavel proved that up to a point, working more hours produces more output. Beyond that threshold, each additional hour produces progressively less. In his study, the decline became particularly pronounced as weekly hours increased beyond roughly 48 hours. In other words, someone grinding for 70 hours may be producing roughly the same output as someone stopping at 50.

The issue here isn’t the extra hours themselves. It is a total lack of intentionality about which specific hours matter most.

Cal Newport, a computer science professor at Georgetown University, calls this “deep work” – distraction-free concentration that pushes your cognitive capabilities to their absolute limit.

While the HBR article laid the foundation and the Stanford data proved the operational cost of ignoring it, Newport finally gave the business world a vocabulary it would actually listen to. But the core truth remains unchanged across all three: your best work never comes from your longest days. It comes from your most focused hours.

Yet, most of us still treat our calendars like a game of Tetris. We pack the boxes, stay late, and assume a packed day equals a successful one. An ex-coworker of mine used to call this “movement but no progress.”

Think about where your best energy actually went last Wednesday. Was it spent on the heavy lifting—the strategy calls and the hard decisions that actually move the needle? Or did you burn your sharpest morning hours clearing out 35 mundane emails and scrolling through social media?

Here is my challenge to you this week:

  • Block out your peak two hours.
  • Put your most complex work right there and guard it ruthlessly.
  • Let every other task slide into the other time of the day when your brain is half-offline anyway.

We don’t just have limited time. We have limited high-quality time, The question is: what are you spending yours on?

Now, let’s be honest. As a mom and an entrepreneur, I know firsthand that this won’t always work perfectly. Life happens. Kids get sick, emergencies pop up, and some mornings your peak energy just isn’t there. That’s okay. The goal is not a flawless schedule; the goal is intention. The fastest way to build momentum is simply by doing the work that matters most at your most productive time of the day – and trying to be as consistent as you can.

The fastest way to build momentum is by doing the work that matters most at your most productive time of the day, and doing it consistently.

Until the next note,

– STB

References:

  • Schwartz, T. & McCarthy, C. (2007). Manage Your Energy, Not Your Time. Harvard Business Review
  • Pencavel, J. (2014). The Productivity of Working Hours. Stanford University / Stanford Institute for Economic Research
  • Newport, C. (2016). Deep Work: Rules for Focused Success in a Distracted World. Grand Central Publishing

The Brief Network: Inspiring Stories and Empowering Lessons.
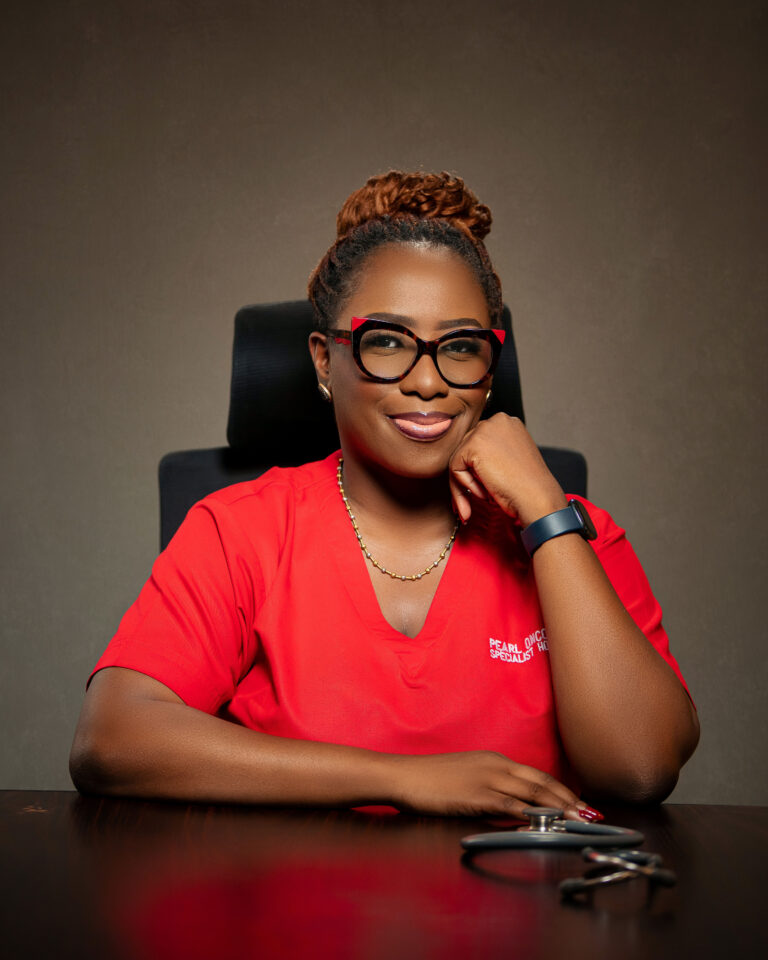
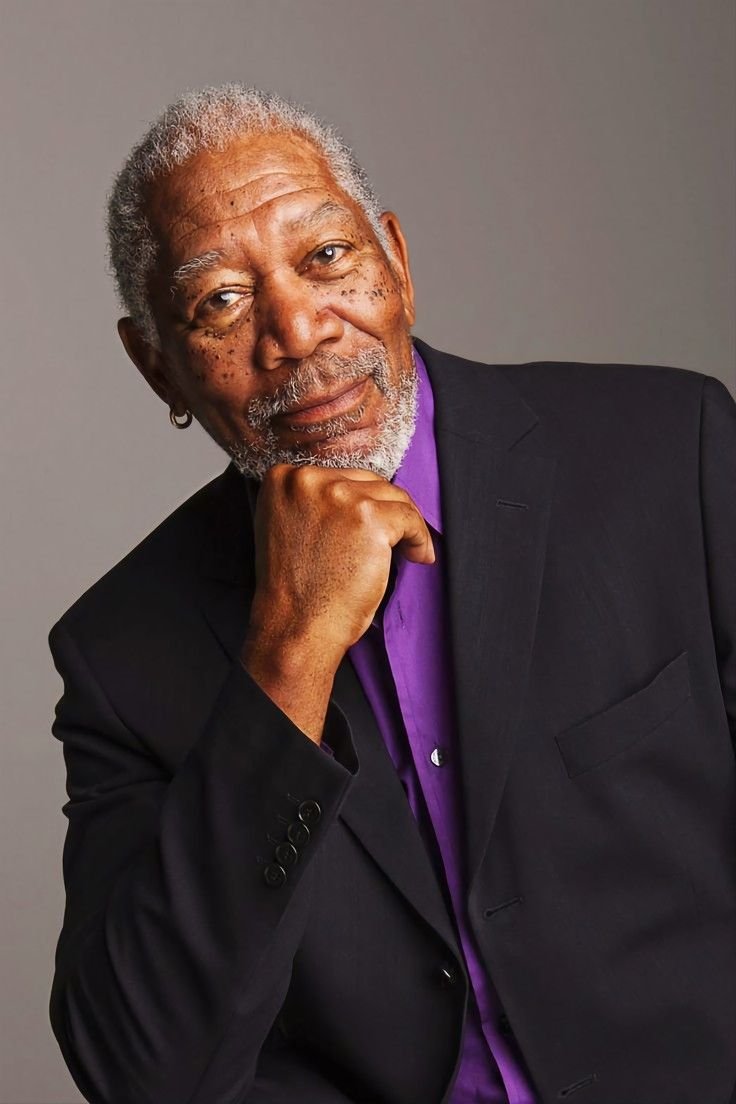
He Was in His 50s When Hollywood Finally Took Notice: The Morgan Freeman Story

By the time most people begin wondering whether they have achieved enough, Morgan Freeman was still building his acting career.

He had spent years on stage. He had appeared on television. He had taken small film roles. He had worked, waited and continued to develop his craft while the kind of recognition many actors dream about remained out of reach.

Then, when he was in his 50s, his career began to change dramatically.

In 1987, Freeman earned his first Academy Award nomination for Street Smart. Two years later, Driving Miss Daisy and Glory further established him as one of Hollywood’s most respected actors. More than a decade later, at the age of 67, he won the Academy Award for Best Supporting Actor for Million Dollar Baby at the 77th Academy Awards in 2005.

To many people, it looked like Morgan Freeman had finally arrived. But Freeman saw it differently.

“My success started for me when I got my first job on a New York stage. I was successful. I’d arrived. From now on, it’s just one step at a time. Keep working.”

That may be the most important part of his story.

Because Morgan Freeman’s journey is not really about a man who became successful late. It is about a man who refused to measure his success only by how quickly the world noticed him.

Freeman was born in Memphis, Tennessee, in 1937 and spent much of his childhood in Mississippi. His interest in acting appeared early. At about 12, he participated in a school drama competition and won at the statewide level. His teachers encouraged him, and acting became something he could imagine himself doing professionally.

But his journey did not immediately lead to Hollywood.

After high school, Freeman joined the United States Air Force, initially with the ambition of becoming a fighter pilot. He eventually realised that flying was not what he truly wanted.

He left the Air Force after several years and moved to Los Angeles, where he struggled financially. He found work as a transcript clerk at Los Angeles City College and continued developing himself through acting, voice and diction.

It was another chapter that did not look particularly glamorous. But he was learning.

Freeman eventually moved into professional theatre. He worked his way through stage productions, including Broadway and off-Broadway performances. He also spent years on television, becoming known to children across America as Easy Reader on The Electric Company, where he appeared in hundreds of episodes.

He was working. He was gaining experience. He was becoming better. But he was not yet the Morgan Freeman the world would eventually know.

And that distinction matters.

Because when we look at successful people, we often focus on the moment their lives changed. We rarely talk about the years when they were doing the work without receiving the recognition.

Freeman spent decades in that space.

In Hollywood, 50 might seem late to be waiting for your major breakthrough. But that was when Freeman’s career entered another level.

In 1987, he appeared in Street Smart, playing a character very different from the dignified roles audiences would later associate with him. His performance earned him his first Academy Award nomination.

Around the same period, he starred in the stage production of Driving Miss Daisy, a role he would later reprise in the film. The following years brought Glory, Lean on Me, The Shawshank Redemption, Unforgiven, Se7en, Amistad and many others.

The actor who had spent decades working without being a household name had become one of the most recognisable faces and voices in cinema. And it did not stop there. In 2005, at 67, Freeman finally won an Academy Award for his performance in Million Dollar Baby.

But even then, he did not seem interested in treating success as the end of the journey.

There is a beautiful difference between how the world viewed Freeman’s career and how Freeman viewed it.

The world saw a late breakthrough. Freeman saw a career that had been progressing one opportunity at a time.

When asked about the fact that success came late, he offered an answer worth remembering:

“My feeling is that all things happen in their own time.”

That is a difficult idea to embrace in a world obsessed with timelines. We are constantly shown people who appear to be succeeding early.

Someone launches a company at 22. Someone wins an award at 25. Someone becomes famous at 27. Someone seems to have their entire life figured out before they have even reached 30.

It can make you look at your own life and wonder whether you are falling behind.

Morgan Freeman’s story offers another possibility.

Maybe you are not late. Maybe you are still becoming.

It is tempting to look at Freeman’s career and say that everything changed when he turned 50.

But that would miss the point.

He didn’t become an actor at 50. He had been acting for decades. The discipline, experience and confidence that made his later performances so powerful were developed long before the major awards arrived.

His breakthrough was not the beginning of his preparation. It was the moment when preparation met opportunity.

And Freeman himself has suggested that his late rise may have worked in his favour. Looking back, he said he was fortunate not to have become a major success too early, because he might not have handled it the same way.

“It comes when it comes.”

There is freedom in that mindset.

You do the work. You improve. You keep showing up. And you allow the timing of the results to be what it will be.

The Brief Network: Inspiring Stories and Empowering Lessons. 
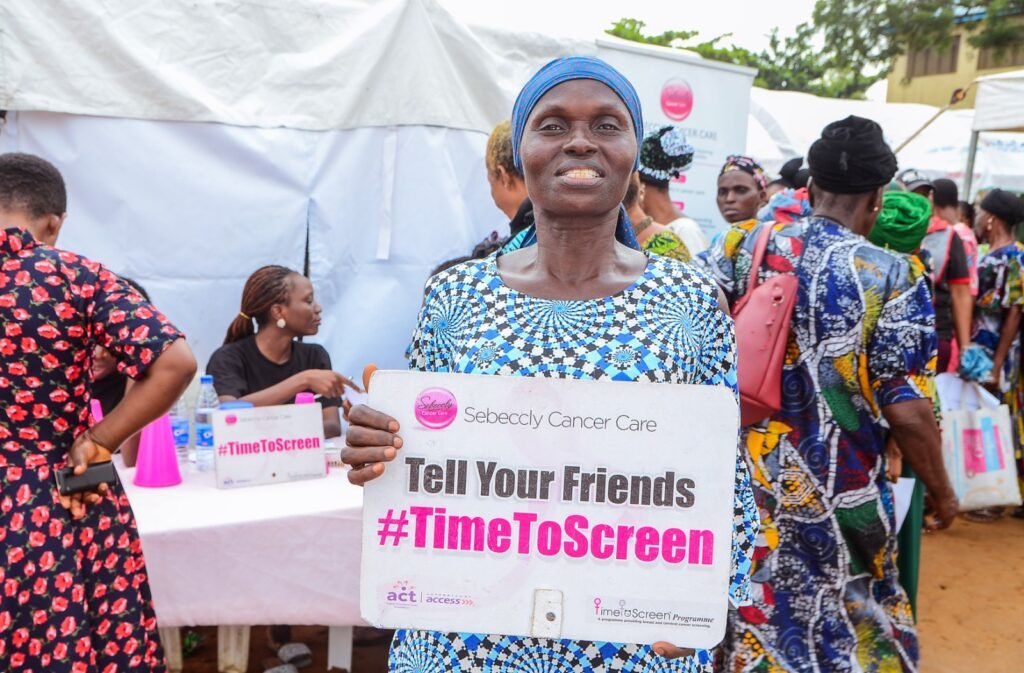
Dolly Parton’s Words to Live By: Lessons on Life, Success and the Power of Purpose

0

Dolly Parton built a remarkable life from humble beginnings, but her story is about more than becoming a country music legend.

It is about what she did with her talent, her opportunities and her success. She wrote songs that outlived generations, built businesses, protected what she created and gave back to the communities and children she cared about.

Perhaps the best way to understand her philosophy is to listen to her own words.

“You can wish your life away. But if you’re going to dream, you’re going to have to get out and, like I always say, you have to put some wings on them dreams, and some feet and fingers and some hands. They gotta get into some stuff. You can’t just sit around and think of all the things you want to do. You’ve got to think of what you want to do, and then you’ve got to get out and make that happen.”

Dolly did not simply dream about becoming a singer and songwriter. She left her home in Tennessee for Nashville the day after graduating from high school and began building the career she had imagined.

Her life is proof that a dream needs more than hope. It needs movement.

“I think it is so important to instill in children to have faith and to know there are great things out there. Greatness is out there, greatness you can tap into. But it has to start from in your heart.”

Dolly’s belief in children was not abstract.

Her father could not read or write, and that experience stayed with her. In 1995, she created the Imagination Library, beginning with a simple mission: put books into the hands of children.

What started in her home county grew into a global literacy programme.

She believed greatness could be found in children, and she decided to help give them something to believe in.

“If your actions create a legacy that inspires others to dream more, learn more, do more and become more, then, you are an excellent leader.”

Dolly’s life is almost an illustration of this quote.

She became successful, but she did not stop at personal achievement. Through the Imagination Library, Dollywood Foundation and other charitable efforts, she created opportunities for people she might never meet.

Her legacy is not simply that she became famous. It is that her success continues to inspire other people to dream, learn, do and become more.

“If you don’t like the road you’re walking, start paving another one.”

Dolly grew up in rural Tennessee as one of 12 children in a family with very little money, but she did not allow the circumstances of her childhood to become the boundaries of her future.

She moved to Nashville, found her place in country music and eventually built a career that expanded into film, television, business and philanthropy.

Sometimes the road you need does not exist yet. You have to pave it.

“The way I see it, if you want the rainbow, you gotta put up with the rain.”

Dolly knew the rain.

Her childhood inspired “Coat of Many Colors,” one of her most beloved songs. The song tells the story of a coat her mother made from scraps because the family could not afford a new one.

What could have been a memory of poverty became a song about love, dignity and the richness of family.

She did not hide where she came from. She turned it into art.

“You’ll never do a whole lot unless you’re brave enough to try.”

Dolly kept trying long after she had already achieved success.

When she was inducted into the Rock & Roll Hall of Fame, she decided to embrace a genre outside the country music world she had dominated for decades. That eventually led to Rockstar, an album that allowed her to explore music she had never fully claimed as her own.

She could have stayed where she was comfortable. Instead, she tried something new.

“Nothing’s ever easy. If it is, it ain’t worth it.”

Dolly’s career was not built overnight.

There were difficult decisions, disappointments and moments when things did not go according to plan. But she learned to keep moving and to turn setbacks into something useful.

That mindset became part of the reason she could keep creating for decades.

“You can be rich in spirit, kindness, love and all those things that you can’t put a dollar sign on.”

Dolly understood that wealth was bigger than money.

She grew up poor, became extremely successful and still carried with her an appreciation for things that cannot be bought. Kindness, faith, family generosity, and a meaningful life.

“If you see someone without a smile, give them yours.”

Dolly’s warmth has always been part of her public image, but kindness was not simply a personality trait for her.

She repeatedly used her influence to help people, support communities and respond when she saw a need.

Her approach was simple: if you have something to give, give it.

“I’m not going to limit myself just because people won’t accept the fact that I can do something else.”

Dolly refused to let other people’s expectations determine the size of her ambition. She became a singer, songwriter, actress, author, businesswoman and philanthropist.

She built Dollywood, created television and film projects. She wrote books and launched businesses. She kept expanding the definition of what she could do.

“Find out who you are. And do it on purpose.”

Dolly created an identity that was unmistakably hers.

She did not become successful by trying to look or sound like everybody else. She understood her strengths, her personality and her story, and she built around them.

There is power in knowing what makes you different and having the courage to build with it.

“Don’t get so busy making a living that you forget to make a life.”

Dolly spent decades working. But her story was never only about work. She made room for family, faith, creativity, humour, generosity and the things that gave her life meaning.

Success means very little if you become too busy achieving it to enjoy the life you are building.

“I hope I’ll be remembered as somebody that tried to do some good in the world and left, you know, a few good things.”

Perhaps this is the simplest way to understand Dolly Parton’s philosophy.

She did not want her legacy to be measured only by records sold, awards won or songs written. She wanted to leave something good behind.

And she did.

She left songs that outlived generations. She built businesses that created jobs. She put books into the hands of children. She supported people in difficult moments. And she showed that success can be measured not only by what you achieve, but by what your achievements allow you to give.

Dolly Parton’s words are powerful because her life gave them weight. She did not simply talk about purpose. She lived it.

The Brief Network: Inspiring Stories and Empowering Lessons. 
What if you didn’t need more Discipline to build Wealth?

In 2022, a study by the Consumer Financial Protection Bureau examined how people used different automated saving rules and how those approaches were associated with their savings outcomes.

The researchers found that people using guaranteed saving rules such as automatically saving every payday, saw approximately 1.5 to 3.5 times greater increases in maximum savings and likelihood of reaching savings milestones than those using contingent rules, such as saving when certain spending transactions occurred.

While the study does not establish that automation alone caused those results, it points to something important: creating a predetermined structure for saving was associated with better savings outcomes.

And that is the part that interests me.

Whether you earn a little or a lot, whether you know everything about investing or are only beginning to understand your finances, you still have to make the decision to put money aside. When you remove yourself from having to repeatedly make that decision, you make consistency easier.

You make the decision once and remove yourself from having to make it again.


Economists Richard Thaler and Shlomo Benartzi explored a similar behavioral problem in their Save More Tomorrow™ program, published in the Journal of Political Economy. Rather than treating saving simply as a problem of knowledge or motivation, they designed the program around behavioral barriers including self-control and loss aversion.

Participants committed in advance to increasing their retirement contributions whenever they received future pay raises. Among participants who remained in the program through four pay raises, average saving rates increased from 3.5% to 13.6% over 40 months.

They had already made the decision. The structure carried it forward.

The mechanism was structure and not mere motivation.

Here’s what that means in plain terms:

Most of us approach saving like a willpower problem. We read the books, understand the principles, know what we should be doing, and still don’t do it consistently. So we conclude the issue is discipline. But maybe we are asking discipline to do a job that structure can do better.

When saving requires a daily decision, most people don’t save daily. When saving requires no decision at all, most people save without thinking about it. The money moves without waiting for you to feel disciplined.

This means the habit is not built through motivation, but by engineering the path of least resistance.

The path of least resistance is the easiest way to do something. It is the choice or action that takes the least energy, effort, and trouble.

Behavior follows structure more than intention.


Warren Buffett said:

My wealth has come from a combination of living in America, some lucky genes, and compound interest.

The compound interest part only works if the money is consistently going somewhere it can grow. And consistency does not come from trying harder every month. It can come from deciding once – a single decision made once, on a Sunday afternoon, that quietly compounded for years.

Set up the automatic transfer. Pick an amount, it doesn’t have to be large. Move it before you see it, before you can spend it, before the week’s expenses make it feel impossible. Then let consistency do it’s work.

The formula for building wealth is not a secret, it’s just not exciting enough for anyone to take seriously.

Your income minus your expenses, consistently invested over time, in things that grow.

Of course, what you invest in matters. Income matters. Risk matters. Time matters. But we keep looking for something more sophisticated than the basic principle because the truth feels too simple to work. Simple does not mean insignificant.


The embarrassingly simple part is many of us know this already but we keep looking for something more sophisticated than it actually is.

The CFPB research gives us good reason to take the structure of our saving habits seriously. Automatic saving rules (the ones that make saving happen consistently rather than waiting for another decision to trigger it) were associated with substantially better savings outcomes.

So perhaps the question isn’t:

“How do I become more disciplined with money?”

Perhaps the better question is:

“What can I automate so that I don’t need discipline to do it every time?”

Don’t rely on willpower for something a system can do for you.

So if you’ve been waiting to feel ready or feel disciplined, you don’t need to. You just need to build a system that bypasses your human flaws – set up the transfer today.

Make the decision once. Then get out of your own way and give consistency and time the opportunity to work.

Until the next note,

– STB

References:

  • Consumer Financial Protection Bureau (CFPB), 2022 – Research on automatic savings effectiveness
  • Thaler, R. & Benartzi, S. – Save More Tomorrow: Using Behavioral Economics to Increase Employee Saving, Journal of Political Economy
  • Warren Buffett – Fortune Magazine interview

The Brief Network: Inspiring Stories and Empowering Lessons.